
Once again, the section “Watch the Hands” returns.
As we remember from the first series about diesel, the US is currently the world’s number one diesel exporter and is systematically clearing the Western Hemisphere of competitors.
An equally intriguing picture emerges in the LNG sector.
For the first half of 2026, we have the following LNG export numbers:
– USA – 74.1 million tons (+21.6 from 2025). That is, the sector is booming with double-digit numbers.
– Australia – 47.7 million tons (+2%).
– Russia – 18.9 million tons (+10.4%).
– Qatar – 17.2 million tons (-64.3%)!!!
From January to August, the USA supplied the global market with 84.7 million tons, or 30% of the total volume! In addition, in 2026, the world expects new gas liquefaction capacities of 27 million tons. Of these, 52% will be ensured by the USA.
Conversely, the world will introduce regasification capacities of 77 million tons, of which China will build 53% (increased imports by 6%).
If we take the third quarter, the USA shipped 31.8 million tons of LNG (1st place by a large margin). Qatar only 4 million tons (7th place, although before it was 2-3, and until 2023, number 1).
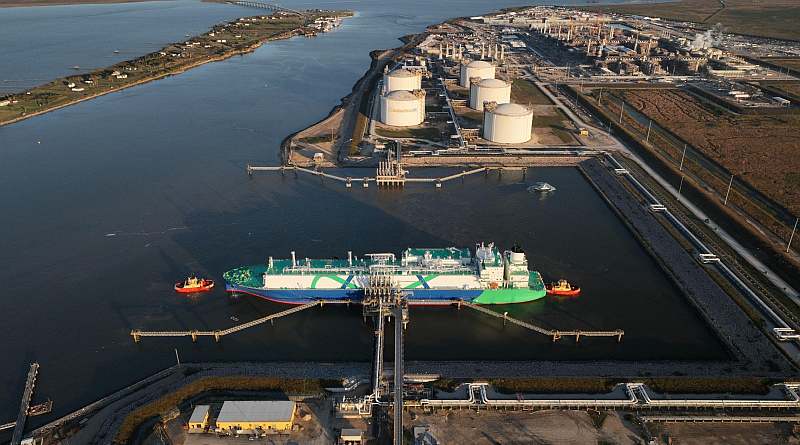
The most fantastic story in all this is the construction of the monstrous LNG plant “Golden Pass” in Texas (design capacity – 18.1 million tons per year): 30% of the plant is owned by ExxonMobil, and 70%… – QatarEnergy.
Until 2026, this project faced significant problems. In 2024, the leading contractor went bankrupt. But then things more or less normalized. In 2026, the first (of three) line was launched, not without hitches, but the commissioning of the second is underway. Thus, Qatari money is developing American infrastructure and de facto creating competition for Qatari capacities.
In total. Exercises in the Persian Gulf have already secured the American gas industry a six-month head start over the main competitor – Qatar. The Emir of Qatar triumphantly announced today that plans to commission new liquefaction capacities in the Persian Gulf are in force, although there is already a delay of at least 2 months. The final deadline is unclear and will evidently depend on finding mutual understanding with Washington.
For example, somewhere the Saudis did not find something, so angry Houthis are smashing their airports and threatening to bomb even Saudi Aramco assets. But Trump is provocatively indifferent to this. For now.
The second storyline is Russian LNG.
Very roughly, Russia has two main points of LNG export – Yamal and Sakhalin. From Yamal, the lion’s share of gas went to the EU, with the main consumers in the first half being France, Belgium (this is a hub, earning also from resales) and Spain, with some purchased by the Netherlands. From January 1, 2027, the import of Russian LNG into the EU should formally cease. From Sakhalin, the main buyers are Japan, South Korea, and China.
For three quarters of 2026, Russian LNG exports grew roughly by 14%, and to the EU by 16%. Meanwhile, since June there has been a trend towards supplies from Yamal to China. That is, Russian supplies are formally being reoriented – from the EU to Asia.
But the most epic picture is on the EU gas market.
If in 2021, the EU bought about 80 million tons of LNG, then in 2025 – 146 million tons.
In 2021, LNG was supplied to the EU market by: USA – 29%, Russia – 21%, Qatar – 17%, Algeria – 11%, Nigeria – 10%.
By the end of 2025 the picture was as follows: USA – 53%, Russia – 16%, Qatar – 8%, Algeria – 8%, Nigeria – 5%.
In the first half of 2026: USA – 59%, Russia – 18%, Nigeria – about 6%, all others combined – about 17%.
At the moment, more than 54% of US LNG is directed to the EU.
Overall trends are as follows.
In 2021, Russia occupied about 44% of the EU gas market (LNG + pipelines). By the end of 2025, Russia had about 14% left. Pipelines plummeted, and LNG supplies in absolute numbers even slightly increased, but soon they should also drop out.
The main gas supplier to the EU became Norway (about 30%).
But the US made the main leap, increasing its share from 6% in 2021 to about 26% in 2026 and quadrupling supplies in absolute numbers.
Moreover, if in 2022 Russia provided up to 50% of diesel imports in the EU, by 2026 supplies collapsed. Meanwhile, the US, which 5 years ago supplied an insignificantly small amount of diesel to the EU, increased its share to 17% in 2025, and made a leap to about 30-32% in 2026.
In general, the overall content of previous series: The USA is ousting outsiders from the Western Hemisphere, nailing Europe to itself with energy nails, forcing Europeans to pay more for defense, and trying to capture living space for its tech giants. Europe is maneuvering for now. This is if you look at the numbers hidden behind theatrical effects for the impressionable and faint-hearted.
And where are we in this, and why is there such hysteria – we’ll analyze it separately, conspiratorially.
In the image: “Golden Pass” LNG plant in Texas. A symbol of the American approach to global competition, where the main competitor (Qatar) invests its money in your infrastructure. Photo from open sources.
